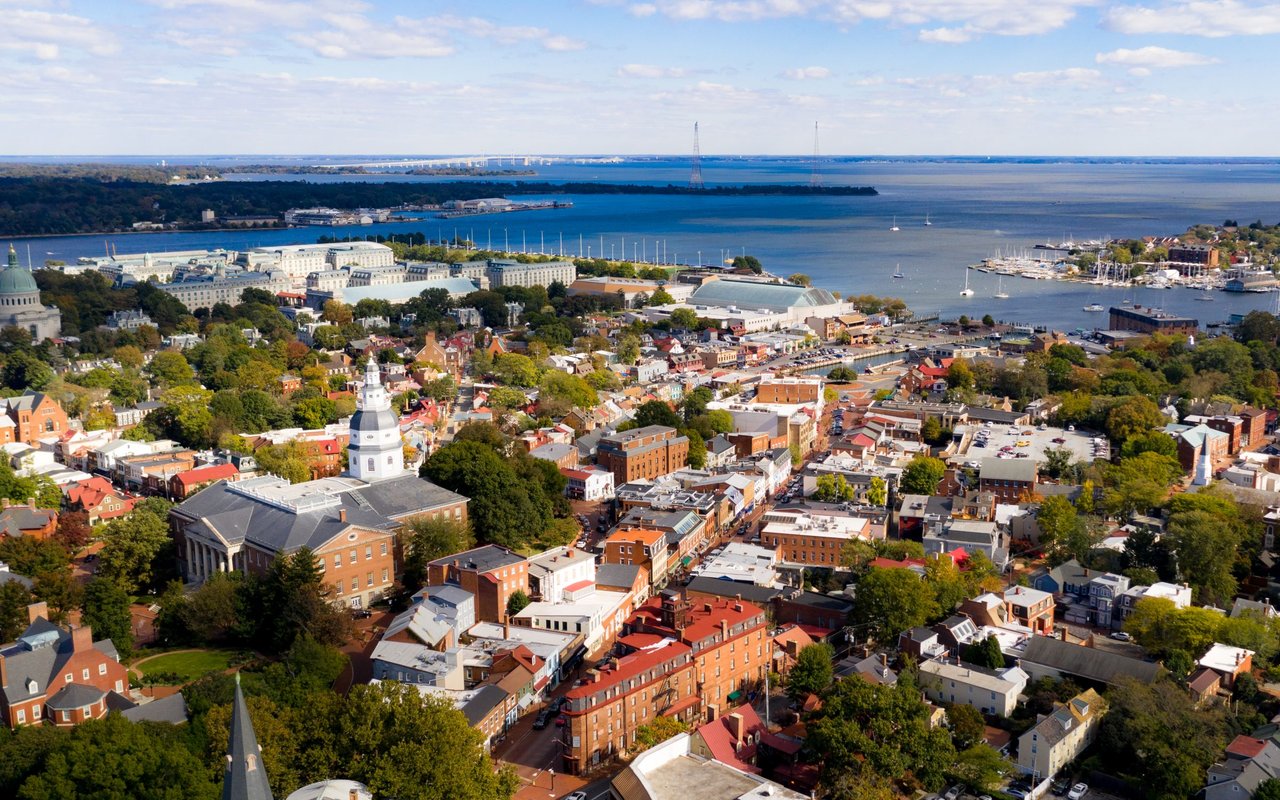
Thinking about buying or holding a rental in Annapolis? It is easy to get pulled in by the city’s waterfront appeal, steady visitor traffic, and strong household incomes, but smart investors know a good-looking property is not always a good rental. If you want to evaluate Annapolis rentals with more discipline, you need to look past headline rent and into the numbers that actually drive return. Let’s break down how to underwrite an Annapolis rental like an investor.
Start With Annapolis Market Reality
Annapolis is not a simple high-cash-flow market. It is Maryland’s state capital, home to the U.S. Naval Academy since 1845, and a city that welcomes more than 4 million visitors a year. That mix of government, military, education, and tourism can support durable rental demand, but it can also make demand more seasonal around major events.
The renter profile also matters. Census data shows a median household income of $113,860, a 62.0% owner-occupied housing rate, median gross rent of $1,860, and 53.8% of adults with a bachelor’s degree or higher. In practical terms, that suggests you are underwriting in a relatively affluent market, not a low-rent market where weak operations can be hidden by high yield.
Current asking-rent data tells a more immediate story. Zillow reports average asking rent around $2,700 with 173 available rentals and a year-over-year increase of $205. That is useful, but it should be paired with longer-run data like Census figures so you do not treat one snapshot as the full market.
Compare Rent to Price First
Your first screen is simple: compare likely rent to acquisition price. Redfin’s April 2026 snapshot puts the median Annapolis sale price at $596,192, while Zillow’s average asking rent is $2,700. That points to a rough gross rental yield of about 5.4% before expenses.
That number matters because it tells you Annapolis usually does not work on a loose back-of-the-envelope model. Monthly rent is only about 0.45% of the current median sale price, which is well below the kind of rule-of-thumb screen some investors use in cheaper, higher-yield markets. In Annapolis, you typically win through disciplined underwriting and strong operations, not by assuming rent alone will save the deal.
Build an Investor Underwriting Model
Once a property passes the first screen, move from gross rent to true performance. A clean underwriting process helps you avoid overpaying for a property that looks fine on the surface but struggles after real costs show up.
Step 1: Underwrite Gross Scheduled Rent
Start with market-supported rent, not your best-case rent. In Annapolis, that means using current comparable rentals and being realistic about whether the property fits the market at the rent you want. If your assumptions sit above what similar rentals are actually asking, your model is already off.
You should also keep lease structure in mind. The City of Annapolis states that long-term rentals under the standard Rental Operating License require at least a one-year lease. If your pro forma assumes short turnover cycles or premium short-duration pricing, make sure that matches the actual permitted use.
Step 2: Apply Vacancy and Collection Loss
Do not underwrite as if every month is fully leased and fully paid. Annapolis has durable demand drivers, but it is still a market where turnover timing, renewal strategy, and seasonal activity can affect occupancy. A vacancy line forces your model to reflect normal friction instead of ideal conditions.
Even a property in a healthy market can lose money during make-ready periods, lease-up gaps, or poorly timed renewals. If the numbers only work at full occupancy all year, the deal is probably too tight.
Step 3: Model Operating Expenses Fully
This is where many rental evaluations go wrong. Annapolis has local costs and compliance items that can materially change net operating income, especially on older housing stock.
At a minimum, your expense review should include:
- Property taxes
- Insurance
- Repairs and maintenance
- Turnover costs
- Property management
- Utilities paid by the owner
- Licensing and registration fees
- Lead compliance costs when applicable
Anne Arundel County notes that property-tax bills may include state taxes and, for properties inside Annapolis, city taxes as separate lines. Bills can also include charges such as solid-waste, stormwater, bay restoration, and special-district taxes. If you underwrite taxes too narrowly, your NOI can be overstated from day one.
Utility assumptions also deserve attention. Annapolis utility rates increased in FY2026, with water and sewer each up 4.75%, refuse up 10%, and watershed restoration up 12%. If you are paying any of these expenses as the owner, they should be modeled with today’s rates rather than last year’s memory.
Factor In Annapolis Rental Compliance
In Annapolis, compliance is not a side issue. It is part of operations, and operations drive returns.
The city requires a Rental Operating License for long-term rentals. The standard license costs $120 per unit per year, renews annually, requires an annual inspection, requires at least a one-year lease, and also requires a pre-1978 lead certificate when applicable. That creates both direct cost and administrative work that should show up in your underwriting.
For pre-1978 properties, Maryland lead-risk rules add another layer. The Maryland Department of the Environment says those rentals must be registered, and the lead rental registration or renewal fee increased to $75 effective January 1, 2026, covering two years. In a city with a meaningful share of older housing stock, that is a real line item, not a footnote.
Why Management Quality Matters
A market like Annapolis can punish sloppy management. Annual inspections, licensing renewals, lead paperwork, maintenance coordination, and utility control all influence your actual NOI. On paper, two owners may buy similar properties, but the one with tighter systems often produces the better return.
That is especially true in a city that actively licenses and inspects rentals. If your management plan is vague, your underwriting is incomplete.
Understand the Rules Around Deposits and Screening
Investor thinking also means understanding the rules that shape leasing risk. Maryland law generally caps security deposits at one month’s rent, allows up to two months only in narrow circumstances, and requires return of the deposit and accrued interest within 45 days after the tenancy ends. If any amount is withheld, a written itemized damage statement is required.
The law also carries teeth. A landlord who withholds a deposit without a reasonable basis can face up to treble damages plus attorney’s fees. That makes move-in documentation, clear records, and consistent property-condition reporting more than good habits. They are risk controls.
Annapolis fair-housing rules are also broader than the federal baseline. The city prohibits discrimination based on source of income, immigration status, citizenship status, and additional protected classes. For investors, that affects how you advertise vacancies, apply screening criteria, and handle vouchers or other assistance payments.
Be Careful With Short-Term Rental Assumptions
Some buyers look at Annapolis and immediately think short-term rental upside. That can be risky if you underwrite the property as one thing and later discover the local rules point another way.
The city regulates short-term rentals separately. Annapolis states that no one lessee may rent for more than 90 consecutive days, while Anne Arundel County defines short-term residential rentals as no more than 120 consecutive days in a calendar year. The occupancy tax is 8% of rent, and city licensing requires either local residency or a local property manager.
If you are evaluating a property as a long-term rental, keep your model based on long-term rental economics. If you are evaluating short-term use, verify the rules, costs, and operating demands separately rather than blending the two into one optimistic spreadsheet.
Calculate Cash Flow After Debt
Once you estimate NOI, the next step is debt service. This is where you learn whether the property is producing actual monthly cash flow or only the appearance of value.
Your path should look like this:
- Start with gross scheduled rent
- Subtract vacancy and collection loss
- Subtract operating expenses
- Arrive at net operating income
- Subtract debt service
- Arrive at pre-tax cash flow
Only after that should you calculate cash-on-cash return. That number tells you how hard your invested cash is actually working after the real-world costs of owning and operating the property.
Treat Appreciation as a Bonus
It is tempting to make a deal work by leaning on future appreciation. That approach is especially dangerous in Annapolis, where citywide pricing can move meaningfully from one year to the next.
Redfin’s April 2026 data shows a median sale price of $596,192, down 14.2% year over year, with homes averaging three offers and 35 days on market. That does not mean Annapolis is weak long term, but it does mean you should avoid using a straight-line appreciation story to justify a thin rental deal.
Instead, use conservative appreciation assumptions and look at neighborhood-specific comparable sales. Annapolis is a historic, waterfront, event-driven market with meaningful differences from one submarket to the next. A disciplined investor stress-tests the exit rather than assuming the market will bail out a weak buy.
A Practical Annapolis Rental Checklist
Before you move forward on any Annapolis rental, ask yourself these questions:
- Is the rent assumption supported by current comparable rentals?
- Have you compared live asking-rent data with longer-run rent context?
- Do taxes include county, city, and other line-item charges where applicable?
- Did you include the $120 annual Rental Operating License cost?
- If the home was built before 1978, did you include lead registration and compliance costs?
- Have you modeled owner-paid utilities using current rate levels?
- Are your vacancy and turnover assumptions realistic?
- Does the property still produce acceptable cash flow after debt service?
- Are you relying on appreciation to save the deal?
- Do you have a clear management plan for inspections, renewals, deposits, and maintenance?
If several of those answers are uncertain, the property may still work, but you need better underwriting before you move ahead.
The Real Investor Mindset in Annapolis
The best Annapolis rentals are usually not the ones with the flashiest listing photos or the easiest story. They are the ones that hold up after taxes, licensing, utilities, compliance, management, vacancy, and debt are all accounted for. In a market with modest gross yield, details matter more.
That is why evaluating Annapolis rentals like an investor means thinking beyond acquisition. You are not just buying a property. You are buying an operating business with local rules, recurring costs, and performance risk that has to be managed well.
If you want a disciplined second look at a deal, or need a partner to help underwrite, operate, or improve a rental in Annapolis, connect with Ryan Brant. Nimble brings investor-grade analysis and white-glove local management to help you protect cash flow and make better real estate decisions.
FAQs
What rent numbers should you use for an Annapolis rental analysis?
- Use both current market asking rents and longer-run housing data for context. In Annapolis, Zillow reports average asking rent around $2,700, while Census data shows median gross rent at $1,860, so it helps to understand what each figure represents before setting your assumptions.
What local license does an Annapolis long-term rental need?
- Annapolis requires a Rental Operating License for long-term rentals. The standard license costs $120 per unit per year, renews annually, requires an annual inspection, and requires at least a one-year lease.
What extra costs matter for older Annapolis rental properties?
- For pre-1978 rentals, lead compliance is a meaningful cost and task. Maryland requires registration for these properties, and the lead rental registration or renewal fee is $75 as of January 1, 2026, covering two years.
How should you think about appreciation for an Annapolis investment property?
- Treat appreciation as a bonus, not the main reason the deal works. Annapolis sale prices can move sharply year to year, so conservative assumptions and neighborhood-specific comparable sales are safer than broad citywide projections.
Why does property management matter so much for Annapolis rentals?
- Strong management affects returns because Annapolis rentals involve annual inspections, licensing, deposit handling, turnover timing, maintenance coordination, and compliance tasks that can directly affect NOI and cash flow.